Turn your mortgage into a wealth-building tool. Smith Manoeuvre strategies, tax-smart planning, and honest math from two Canadian mortgage strategists.
You Don't Need Tenants to Make Your Mortgage Interest Tax-Deductible
A $200,000 home equity line of credit at 6% costs you $12,000 in interest each year. If you're in the 53.53% tax bracket in Ontario, that same $12,000 costs the Canada Revenue Agency $6,416 in foregone revenue, if the loan meets the Income Tax Act's test for deductibility. Most Canadians think the only way to meet that test is to own rental property. They're wrong. The test isn't about being a landlord. It's about using borrowed money to earn income.
The Smith Manoeuvre™ is a structured strategy that converts your non-deductible mortgage interest into tax-deductible investment interest without requiring you to manage tenants, fix toilets, or concentrate 80% of your net worth in a single physical asset. It works through a re-advanceable mortgage: a standard mortgage term paired with a home equity line of credit that expands automatically as you pay down the principal. Every $1,000 of mortgage principal you retire increases your HELOC limit by $1,000. You borrow that $1,000 back through the HELOC and invest it in dividend-paying stocks or income-generating ETFs. The interest on that $1,000 is now deductible because the borrowed funds are being used to earn income, specifically, dividends or interest.
Why this isn't just "landlording with extra steps"
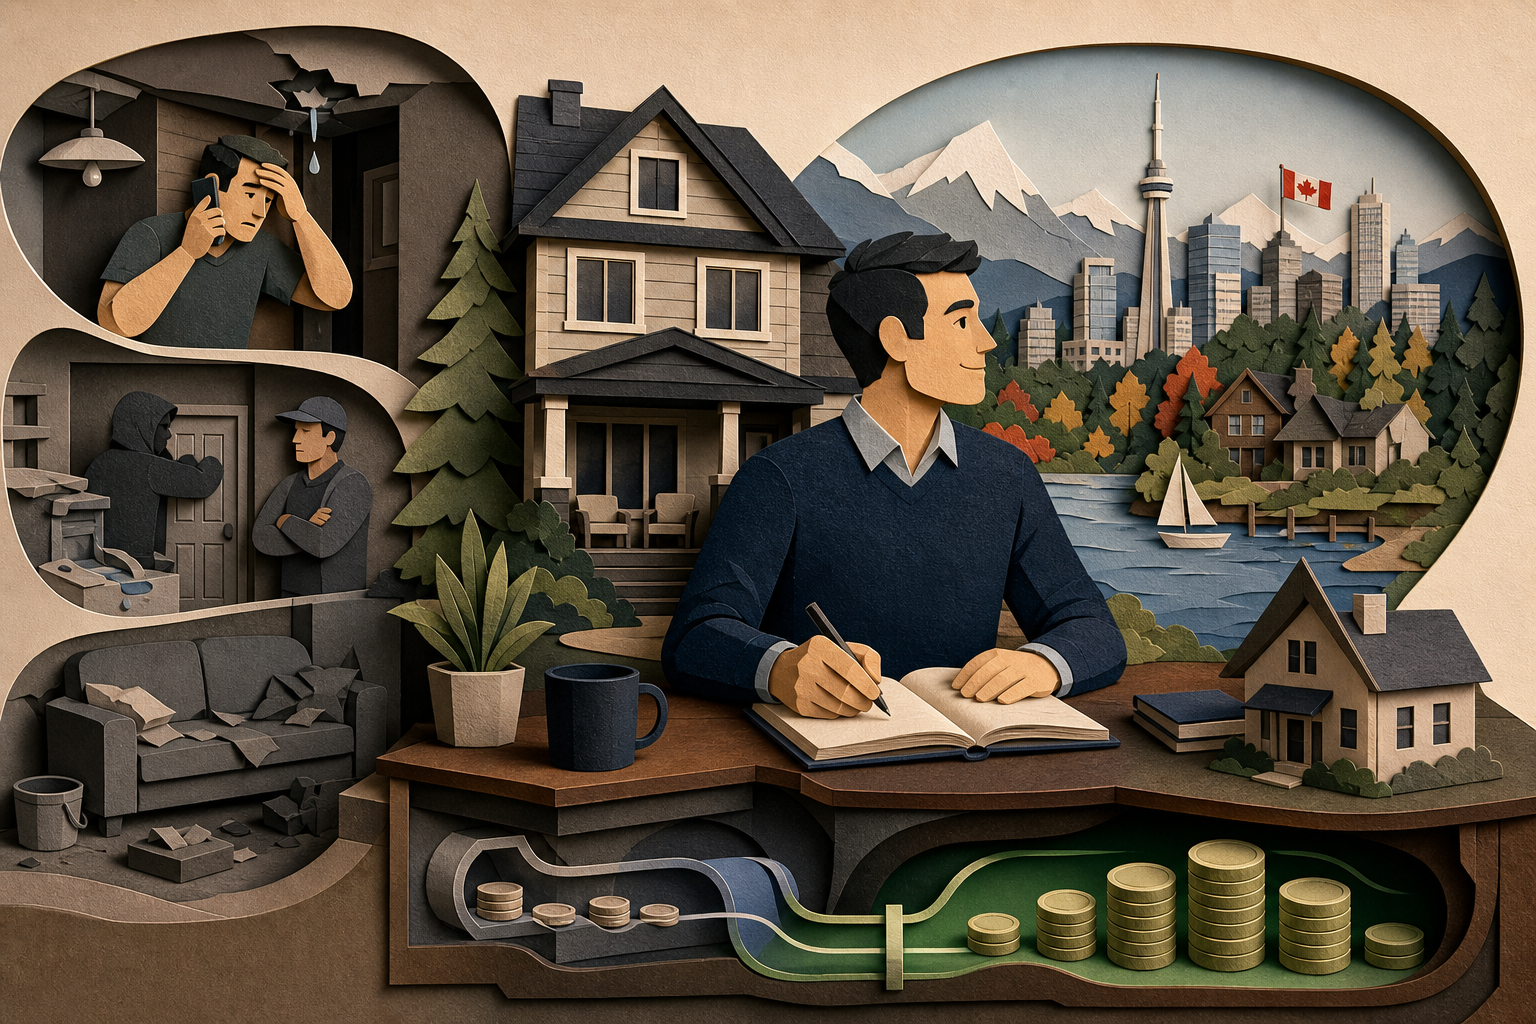
The operational difference is zero physical labour. No late-night calls about a broken furnace. No tenant turnover every eighteen months. No property tax appeals or basement floods. The CRA cares about the purpose of the loan, not the asset class. Interest on money borrowed to earn rental income is deductible. So is interest on money borrowed to earn dividend income. The Act doesn't privilege real estate. It privileges income-producing use.
The tax refund generated by the deductible interest, call it $6,416 in the example above, gets directed straight back into the mortgage principal. That accelerates your payoff, which increases your available HELOC room faster, which lets you invest more, which generates a larger deduction the following year. The cycle compounds. The common objection is that this strategy keeps your total debt level constant for longer. True. But the non-deductible portion shrinks every month while the deductible portion grows. You're trading mortgage debt for investment debt at a pace the tax code subsidizes.
The risk profile differs sharply from rental real estate. With a rental property, you accept tenant risk: non-payment, damage, vacancy. Market risk exists but moves slowly, real estate doesn't gap down 8% overnight. With the Smith Manoeuvre™, you accept market risk: your equity portfolio can drop 15% in a quarter. But tenant risk disappears entirely, and liquidity improves. Selling 500 shares of a Canadian bank ETF takes two business days. Selling a duplex takes four months if the market cooperates.
The compliance requirement most people miss
The CRA's reasonable-expectation-of-income test is not decorative. If you use the HELOC to buy a car or fund a vacation, that portion of the interest immediately loses its deductible status. The trail must stay clean. Every dollar borrowed through the re-advanceable structure must flow directly into an income-producing investment. Capital gains alone don't satisfy the test, the investment must generate dividends or interest while you hold it. This is why Canadian dividend aristocrats and broad equity ETFs with distribution yields above 2% are the typical vehicles. Growth stocks that pay no dividend don't qualify.
The strategy does not eliminate risk. It shifts it. If HELOC rates rise faster than your portfolio's expected return, the spread narrows, though the tax benefit remains. If you cannot tolerate watching your investment account fluctuate by five figures in a bad month, this approach will keep you awake. But if your alternative was becoming a landlord to access the same tax treatment, the Smith Manoeuvre™ offers the deduction without the second job.



A $200,000 home equity line of credit at 6% costs you $12,000 in interest each year. If you're in the 53.53% tax bracket in Ontario, that same $12,000 costs the Canada Revenue Agency $6,416 in foregone revenue, if the loan meets the Income Tax Act's test for deductibility. Most Canadians think the only way to meet that test is to own rental property. They're wrong. The test isn't about being a landlord. It's about using borrowed money to earn income.
The Smith Manoeuvre™ is a structured strategy that converts your non-deductible mortgage interest into tax-deductible investment interest without requiring you to manage tenants, fix toilets, or concentrate 80% of your net worth in a single physical asset. It works through a re-advanceable mortgage: a standard mortgage term paired with a home equity line of credit that expands automatically as you pay down the principal. Every $1,000 of mortgage principal you retire increases your HELOC limit by $1,000. You borrow that $1,000 back through the HELOC and invest it in dividend-paying stocks or income-generating ETFs. The interest on that $1,000 is now deductible because the borrowed funds are being used to earn income, specifically, dividends or interest.
Why this isn't just "landlording with extra steps"
The operational difference is zero physical labour. No late-night calls about a broken furnace. No tenant turnover every eighteen months. No property tax appeals or basement floods. The CRA cares about the purpose of the loan, not the asset class. Interest on money borrowed to earn rental income is deductible. So is interest on money borrowed to earn dividend income. The Act doesn't privilege real estate. It privileges income-producing use.
The tax refund generated by the deductible interest, call it $6,416 in the example above, gets directed straight back into the mortgage principal. That accelerates your payoff, which increases your available HELOC room faster, which lets you invest more, which generates a larger deduction the following year. The cycle compounds. The common objection is that this strategy keeps your total debt level constant for longer. True. But the non-deductible portion shrinks every month while the deductible portion grows. You're trading mortgage debt for investment debt at a pace the tax code subsidizes.
The risk profile differs sharply from rental real estate. With a rental property, you accept tenant risk: non-payment, damage, vacancy. Market risk exists but moves slowly, real estate doesn't gap down 8% overnight. With the Smith Manoeuvre™, you accept market risk: your equity portfolio can drop 15% in a quarter. But tenant risk disappears entirely, and liquidity improves. Selling 500 shares of a Canadian bank ETF takes two business days. Selling a duplex takes four months if the market cooperates.
The compliance requirement most people miss
The CRA's reasonable-expectation-of-income test is not decorative. If you use the HELOC to buy a car or fund a vacation, that portion of the interest immediately loses its deductible status. The trail must stay clean. Every dollar borrowed through the re-advanceable structure must flow directly into an income-producing investment. Capital gains alone don't satisfy the test, the investment must generate dividends or interest while you hold it. This is why Canadian dividend aristocrats and broad equity ETFs with distribution yields above 2% are the typical vehicles. Growth stocks that pay no dividend don't qualify.
The strategy does not eliminate risk. It shifts it. If HELOC rates rise faster than your portfolio's expected return, the spread narrows, though the tax benefit remains. If you cannot tolerate watching your investment account fluctuate by five figures in a bad month, this approach will keep you awake. But if your alternative was becoming a landlord to access the same tax treatment, the Smith Manoeuvre™ offers the deduction without the second job.
Sources
Read Next
Wells Fargo Says Rising Bond Yields Should Force You to Rethink Your Stock Portfolio
At the Top Tax Bracket, Every Dollar of Rental Interest Returns 53 Cents: Why the Smith Manoeuvre™ Is a High-Income Play
China's Treasury retreat to record lows rewrites the rules for bond investors
GIC Rates Below 4.2% Flip the Smith Manoeuvre™ Math From Marginal to Compelling