Turn your mortgage into a wealth-building tool. Smith Manoeuvre strategies, tax-smart planning, and honest math from two Canadian mortgage strategists.
Ottawa keeps promising tax reform. Here's why it won't happen.
Ottawa keeps promising tax reform. Here's why it won't happen.
The Income Tax Act was last fundamentally restructured on January 1, 1971. Today it over 1,400 pages, administers over 100 different tax credits and benefits, and costs Canadian households north of $500 annually just to comply with, professional fees, software, time spent hunting receipts. CPA Canada has been asking for a royal commission to simplify the system for years. Finance ministers from both parties have nodded along. Nothing moves.
The problem isn't technical. Tax policy specialists could design a cleaner code in six months if you locked them in a room. The problem is political arithmetic, and the arithmetic is brutal.
Every credit has a constituency
Tax expenditures, the exemptions, deductions, and credits embedded in the code, cost Ottawa substantial forgone revenue, according to Finance Canada's own reports. That's not waste. That's intentional policy dressed up as tax breaks. The home accessibility credit. The volunteer firefighter amount. The children's arts credit that came and went. Each one was created because a minister wanted to be seen solving a problem without the visibility of new spending.
Remove any of them and you generate an identifiable group of losers. They have names, postal codes, and MPs. The gains from simplification, faster filing, lower compliance costs, a code people can actually read, are diffuse. Diffuse benefits do not win elections. Angry constituencies do.
A revenue-neutral reform that flattened the code and eliminated half the boutique credits might make the system fairer and more efficient. It would also produce dozens of angry op-eds from exactly the groups those credits were designed to please, and not one voter will call their MP to say thank you for making Schedule 1 shorter.
The federal-provincial knot
Most provinces except Quebec use the federal definition of taxable income as their starting point. Any major federal overhaul forces every provincial finance ministry to recalculate their own brackets, credits, and revenue projections. That requires coordination across 10 jurisdictions, each with different fiscal priorities and election cycles.
When the federal government proposed increasing the capital gains inclusion rate from 50% to 66.7% for gains over $250,000 in Budget 2024, it triggered months of modelling work in provincial capitals before the measure was ultimately cancelled in early 2025. That was a single line item. A structural reform touching dozens of definitions would require multi-year federal-provincial negotiations, and the last time Ottawa tried anything close to that scale was the early 1990s harmonization talks. Several of those ended in litigation.
The complexity isn't an accident. It's a buffer. It ensures that sweeping reform requires not just political will in Ottawa but also synchronized will across every provincial treasury board. That synchronization has not existed in 30 years and shows no sign of forming.
Certainty is worth something
Businesses build long-term capital plans around the existing code. A manufacturing firm structuring its depreciation schedule or a venture fund planning its carried interest treatment needs to know the rules won't shift halfway through the investment horizon. The current code is a mess, but it's a predictable mess. Investors price that in.
A genuine structural reform creates a window of regime uncertainty. New definitions of income, new treatment of deductions, new rules for what counts as a capital gain, all of that has to be modelled, litigated, and stress-tested in real transactions. Even a well-designed reform imposes transition costs that exceed the immediate gains for any firm with more than $10 million in revenue.
The Fraser Institute estimates compliance costs at over $500 per household. That's real. But for a business with cross-border operations or complex ownership, the cost of adapting to a rewritten code could run six figures. The status quo is expensive. Change is more expensive, at least in year one.


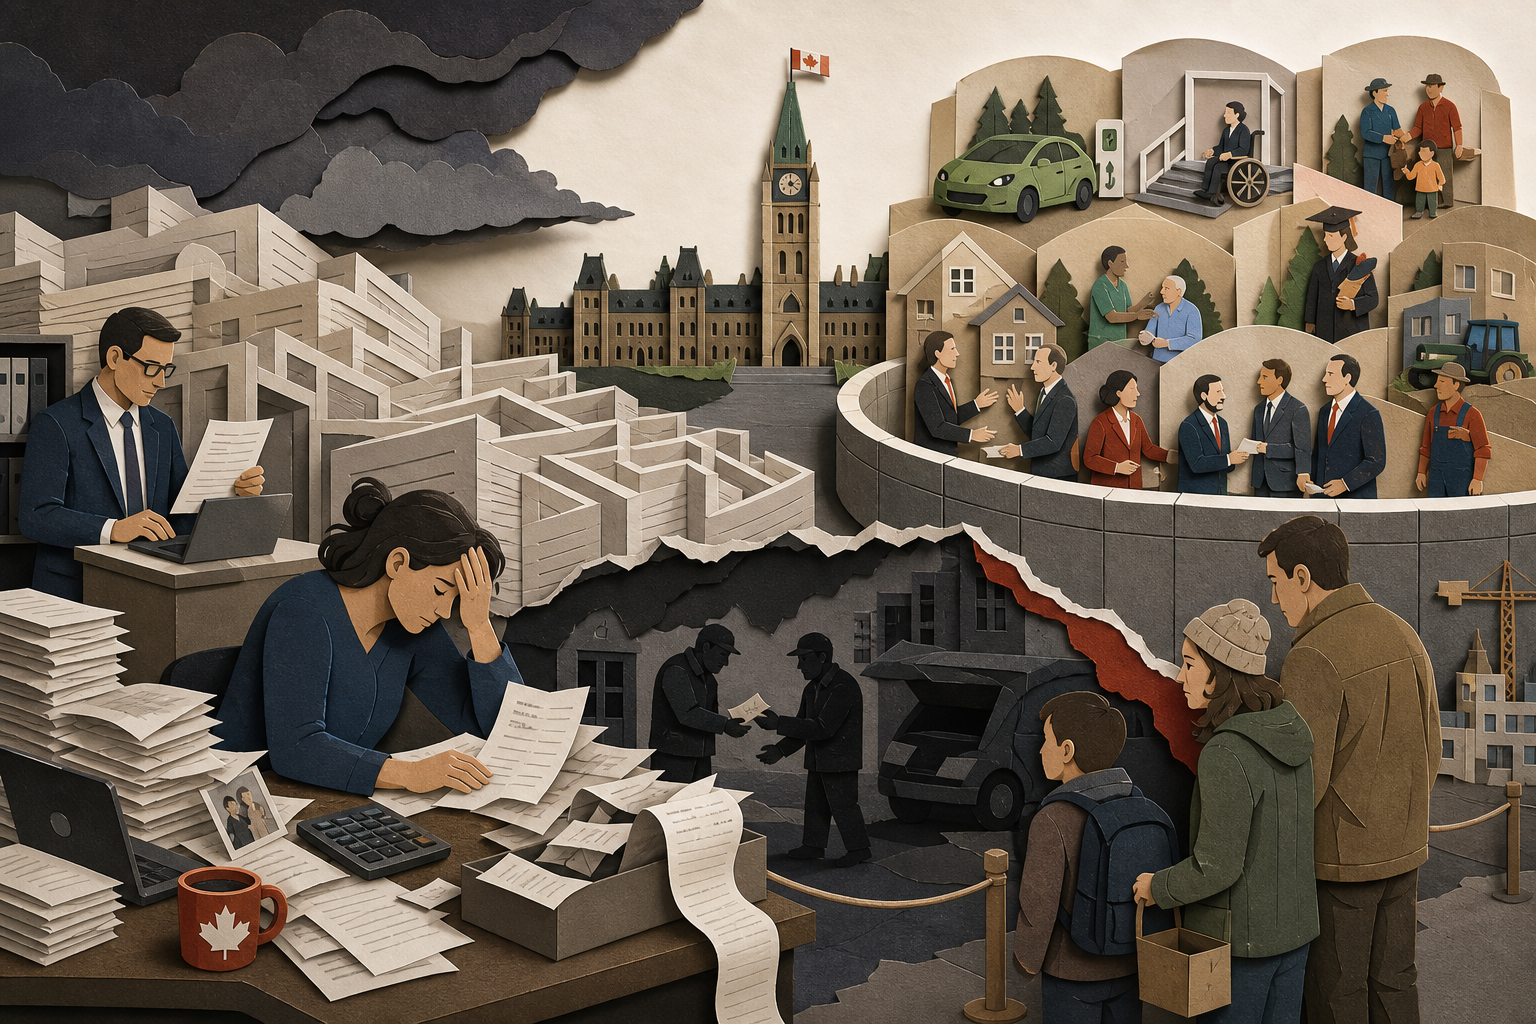

Ottawa keeps promising tax reform. Here's why it won't happen.
The Income Tax Act was last fundamentally restructured on January 1, 1971. Today it over 1,400 pages, administers over 100 different tax credits and benefits, and costs Canadian households north of $500 annually just to comply with, professional fees, software, time spent hunting receipts. CPA Canada has been asking for a royal commission to simplify the system for years. Finance ministers from both parties have nodded along. Nothing moves.
The problem isn't technical. Tax policy specialists could design a cleaner code in six months if you locked them in a room. The problem is political arithmetic, and the arithmetic is brutal.
Every credit has a constituency
Tax expenditures, the exemptions, deductions, and credits embedded in the code, cost Ottawa substantial forgone revenue, according to Finance Canada's own reports. That's not waste. That's intentional policy dressed up as tax breaks. The home accessibility credit. The volunteer firefighter amount. The children's arts credit that came and went. Each one was created because a minister wanted to be seen solving a problem without the visibility of new spending.
Remove any of them and you generate an identifiable group of losers. They have names, postal codes, and MPs. The gains from simplification, faster filing, lower compliance costs, a code people can actually read, are diffuse. Diffuse benefits do not win elections. Angry constituencies do.
A revenue-neutral reform that flattened the code and eliminated half the boutique credits might make the system fairer and more efficient. It would also produce dozens of angry op-eds from exactly the groups those credits were designed to please, and not one voter will call their MP to say thank you for making Schedule 1 shorter.
The federal-provincial knot
Most provinces except Quebec use the federal definition of taxable income as their starting point. Any major federal overhaul forces every provincial finance ministry to recalculate their own brackets, credits, and revenue projections. That requires coordination across 10 jurisdictions, each with different fiscal priorities and election cycles.
When the federal government proposed increasing the capital gains inclusion rate from 50% to 66.7% for gains over $250,000 in Budget 2024, it triggered months of modelling work in provincial capitals before the measure was ultimately cancelled in early 2025. That was a single line item. A structural reform touching dozens of definitions would require multi-year federal-provincial negotiations, and the last time Ottawa tried anything close to that scale was the early 1990s harmonization talks. Several of those ended in litigation.
The complexity isn't an accident. It's a buffer. It ensures that sweeping reform requires not just political will in Ottawa but also synchronized will across every provincial treasury board. That synchronization has not existed in 30 years and shows no sign of forming.
Certainty is worth something
Businesses build long-term capital plans around the existing code. A manufacturing firm structuring its depreciation schedule or a venture fund planning its carried interest treatment needs to know the rules won't shift halfway through the investment horizon. The current code is a mess, but it's a predictable mess. Investors price that in.
A genuine structural reform creates a window of regime uncertainty. New definitions of income, new treatment of deductions, new rules for what counts as a capital gain, all of that has to be modelled, litigated, and stress-tested in real transactions. Even a well-designed reform imposes transition costs that exceed the immediate gains for any firm with more than $10 million in revenue.
The Fraser Institute estimates compliance costs at over $500 per household. That's real. But for a business with cross-border operations or complex ownership, the cost of adapting to a rewritten code could run six figures. The status quo is expensive. Change is more expensive, at least in year one.
No finance minister wants to own year one.
Sources
Read Next
Wells Fargo Says Rising Bond Yields Should Force You to Rethink Your Stock Portfolio
At the Top Tax Bracket, Every Dollar of Rental Interest Returns 53 Cents: Why the Smith Manoeuvre™ Is a High-Income Play
China's Treasury retreat to record lows rewrites the rules for bond investors
GIC Rates Below 4.2% Flip the Smith Manoeuvre™ Math From Marginal to Compelling