Turn your mortgage into a wealth-building tool. Smith Manoeuvre strategies, tax-smart planning, and honest math from two Canadian mortgage strategists.
If You're Afraid the Trade War Will Crash Stocks, You've Already Failed Financial Planning
If You're Afraid the Trade War Will Crash Stocks, You've Already Failed Financial Planning
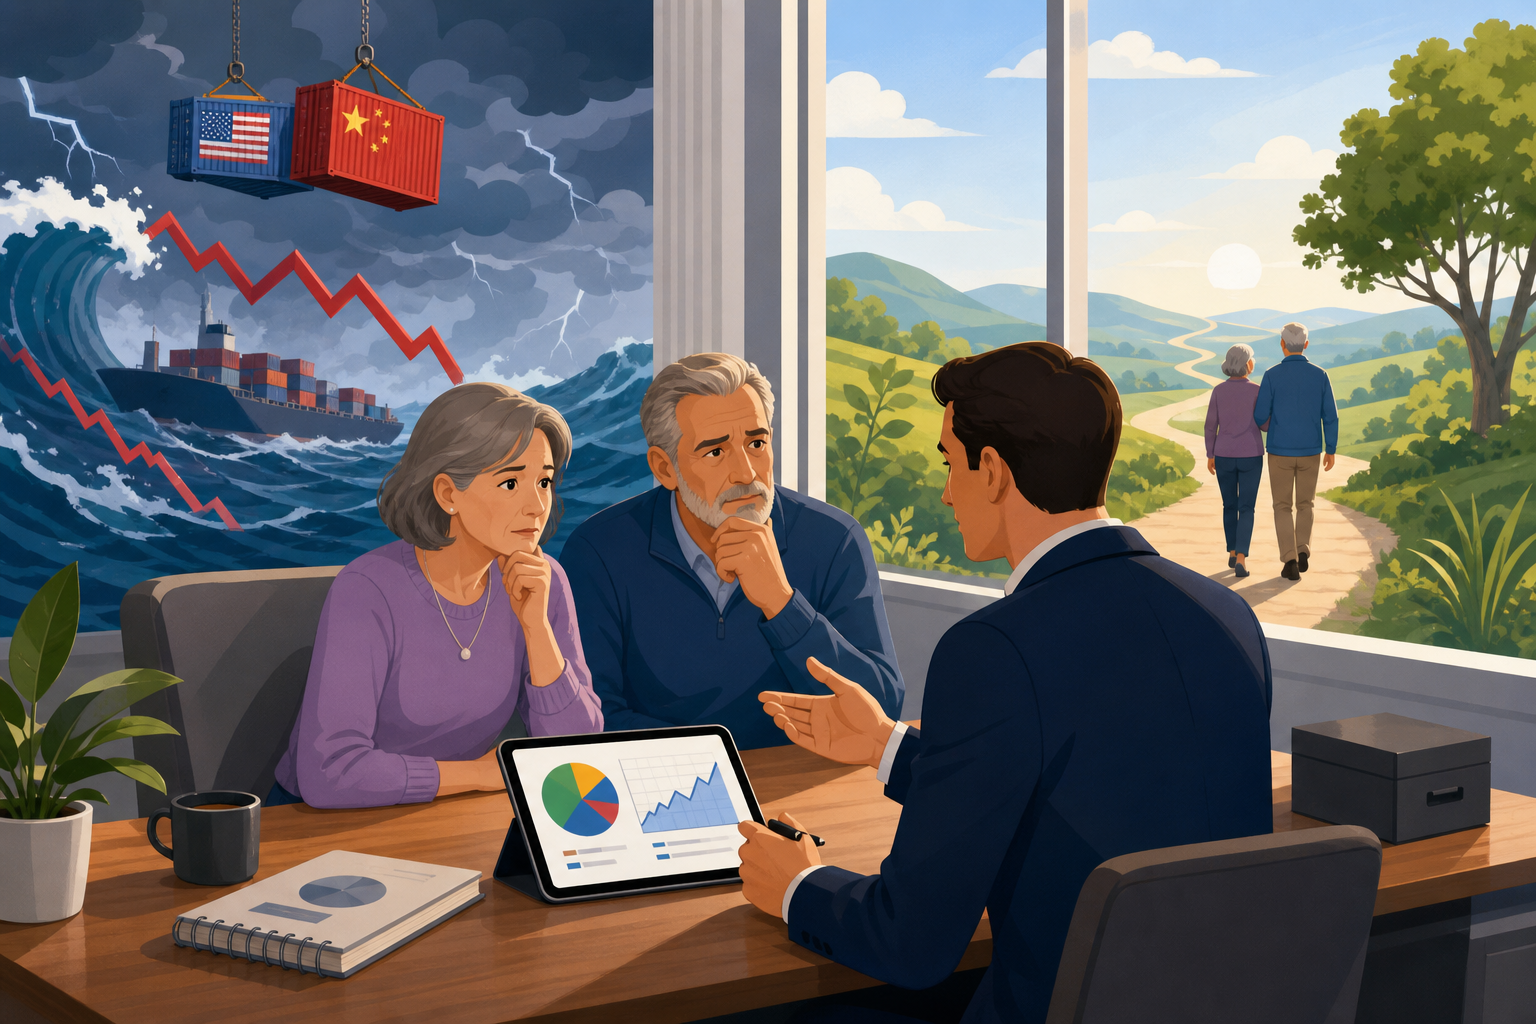
A couple in their early sixties sits across from their advisor in September 2026, asking whether they should pull money out of equities before tariffs "do real damage." They have $1.2 million in registered accounts, a paid-off house, and a plan built three years ago that assumed sequence-of-returns risk. The advisor asks one question: How many months of cash do you have set aside? The answer is four weeks.
This couple has built a retirement structure that requires them to predict headlines.
Why the catalyst never matters
Financial plans are designed to withstand what the industry calls exogenous shocks, events originating outside your control. A pandemic. A geopolitical crisis. A shift in trade policy that realigns supply chains for a decade. The specific trigger changes every cycle, but the mechanics of a market correction do not.
The S&P 500 experiences a 10% pullback roughly once every 18 months (approximately every 1.5 years) on average. Some are driven by interest rate moves, some by earnings disappointments, some by external shocks like tariffs. Investors who wait to identify the "right" cause before acting are solving the wrong problem. By the time you know what caused the downturn, you are already in it, and your choices have narrowed.
Portfolio construction treats volatility as a permanent feature, not a bug to be timed. Standard deviation in annual returns is baked into the projections your advisor shows you. A plan that only works if stocks never drop 15% in a single quarter is not a plan.
What a working plan actually contains
The mechanics are straightforward. You need liquidity that lets you avoid selling equities during a trough. For retirees, this typically means one to three years of living expenses held in cash or high-quality short-term government bonds. The exact amount depends on your withdrawal rate and your tolerance for watching your equity balance fluctuate.
That cash reserve is not "sitting idle." It is doing the job of keeping you from liquidating a growth asset at the worst possible time. When the market drops 18% because tariffs disrupted semiconductor supply chains, you spend from the cash bucket. When the market recovers, and historical data shows it has, across every modern correction, you refill the cash from gains in the portfolio. This is rebalancing, and it forces you to buy low without requiring emotional discipline.
Diversification works the same way. Bonds don't eliminate risk. They reduce the speed at which your total portfolio drops when equities sell off. During the initial months of uncertainty around new trade barriers, a 60/40 portfolio might fall 12% while an all-equity portfolio falls 20%. That difference is the margin that lets you sleep and stick to the plan.
The emotional tax you cannot afford
Loss aversion, the psychological tendency to feel a loss twice as intensely as an equivalent gain, leads investors to abandon plans at precisely the moment those plans are being tested. Selling after a 15% drop to "preserve what's left" locks in the loss and eliminates your exposure to the recovery. The market's strongest days often occur within weeks of its worst ones. Missing those days is expensive.
Frequent trading in response to news is functionally a tax on your wealth. You pay it in transaction costs, in the bid-ask spread, and most damagingly, in the statistical likelihood that you will re-enter the market after it has already climbed back.
Retirement spans thirty years. A trade war might span three. Short-term volatility is noise measured against the long-term signal of compound growth. Tariffs will eventually settle into a new equilibrium or be repealed. Your cash-flow needs in 2041 will not change because of what happened in 2026.
What you can still control
You cannot influence trade policy. You can control your savings rate, your asset allocation, and whether you check your portfolio balance daily or quarterly. You can ask your advisor to stress-test your current plan against a sustained 20% equity drawdown and show you, in dollar terms, whether your withdrawals still hold.
If the answer is no, you need more cash set aside, a lower withdrawal rate, or a longer timeline before you need the money.
A working plan is built so the news does not matter.



If You're Afraid the Trade War Will Crash Stocks, You've Already Failed Financial Planning
A couple in their early sixties sits across from their advisor in September 2026, asking whether they should pull money out of equities before tariffs "do real damage." They have $1.2 million in registered accounts, a paid-off house, and a plan built three years ago that assumed sequence-of-returns risk. The advisor asks one question: How many months of cash do you have set aside? The answer is four weeks.
This couple has built a retirement structure that requires them to predict headlines.
Why the catalyst never matters
Financial plans are designed to withstand what the industry calls exogenous shocks, events originating outside your control. A pandemic. A geopolitical crisis. A shift in trade policy that realigns supply chains for a decade. The specific trigger changes every cycle, but the mechanics of a market correction do not.
The S&P 500 experiences a 10% pullback roughly once every 18 months (approximately every 1.5 years) on average. Some are driven by interest rate moves, some by earnings disappointments, some by external shocks like tariffs. Investors who wait to identify the "right" cause before acting are solving the wrong problem. By the time you know what caused the downturn, you are already in it, and your choices have narrowed.
Portfolio construction treats volatility as a permanent feature, not a bug to be timed. Standard deviation in annual returns is baked into the projections your advisor shows you. A plan that only works if stocks never drop 15% in a single quarter is not a plan.
What a working plan actually contains
The mechanics are straightforward. You need liquidity that lets you avoid selling equities during a trough. For retirees, this typically means one to three years of living expenses held in cash or high-quality short-term government bonds. The exact amount depends on your withdrawal rate and your tolerance for watching your equity balance fluctuate.
That cash reserve is not "sitting idle." It is doing the job of keeping you from liquidating a growth asset at the worst possible time. When the market drops 18% because tariffs disrupted semiconductor supply chains, you spend from the cash bucket. When the market recovers, and historical data shows it has, across every modern correction, you refill the cash from gains in the portfolio. This is rebalancing, and it forces you to buy low without requiring emotional discipline.
Diversification works the same way. Bonds don't eliminate risk. They reduce the speed at which your total portfolio drops when equities sell off. During the initial months of uncertainty around new trade barriers, a 60/40 portfolio might fall 12% while an all-equity portfolio falls 20%. That difference is the margin that lets you sleep and stick to the plan.
The emotional tax you cannot afford
Loss aversion, the psychological tendency to feel a loss twice as intensely as an equivalent gain, leads investors to abandon plans at precisely the moment those plans are being tested. Selling after a 15% drop to "preserve what's left" locks in the loss and eliminates your exposure to the recovery. The market's strongest days often occur within weeks of its worst ones. Missing those days is expensive.
Frequent trading in response to news is functionally a tax on your wealth. You pay it in transaction costs, in the bid-ask spread, and most damagingly, in the statistical likelihood that you will re-enter the market after it has already climbed back.
Retirement spans thirty years. A trade war might span three. Short-term volatility is noise measured against the long-term signal of compound growth. Tariffs will eventually settle into a new equilibrium or be repealed. Your cash-flow needs in 2041 will not change because of what happened in 2026.
What you can still control
You cannot influence trade policy. You can control your savings rate, your asset allocation, and whether you check your portfolio balance daily or quarterly. You can ask your advisor to stress-test your current plan against a sustained 20% equity drawdown and show you, in dollar terms, whether your withdrawals still hold.
If the answer is no, you need more cash set aside, a lower withdrawal rate, or a longer timeline before you need the money.
A working plan is built so the news does not matter.
Sources
Read Next
Wells Fargo Says Rising Bond Yields Should Force You to Rethink Your Stock Portfolio
At the Top Tax Bracket, Every Dollar of Rental Interest Returns 53 Cents: Why the Smith Manoeuvre™ Is a High-Income Play
China's Treasury retreat to record lows rewrites the rules for bond investors
GIC Rates Below 4.2% Flip the Smith Manoeuvre™ Math From Marginal to Compelling