Turn your mortgage into a wealth-building tool. Smith Manoeuvre strategies, tax-smart planning, and honest math from two Canadian mortgage strategists.
How Smith Manoeuvre™ Tax Refunds Accelerate Mortgage Payoff: The Refund Loop Advisors Miss
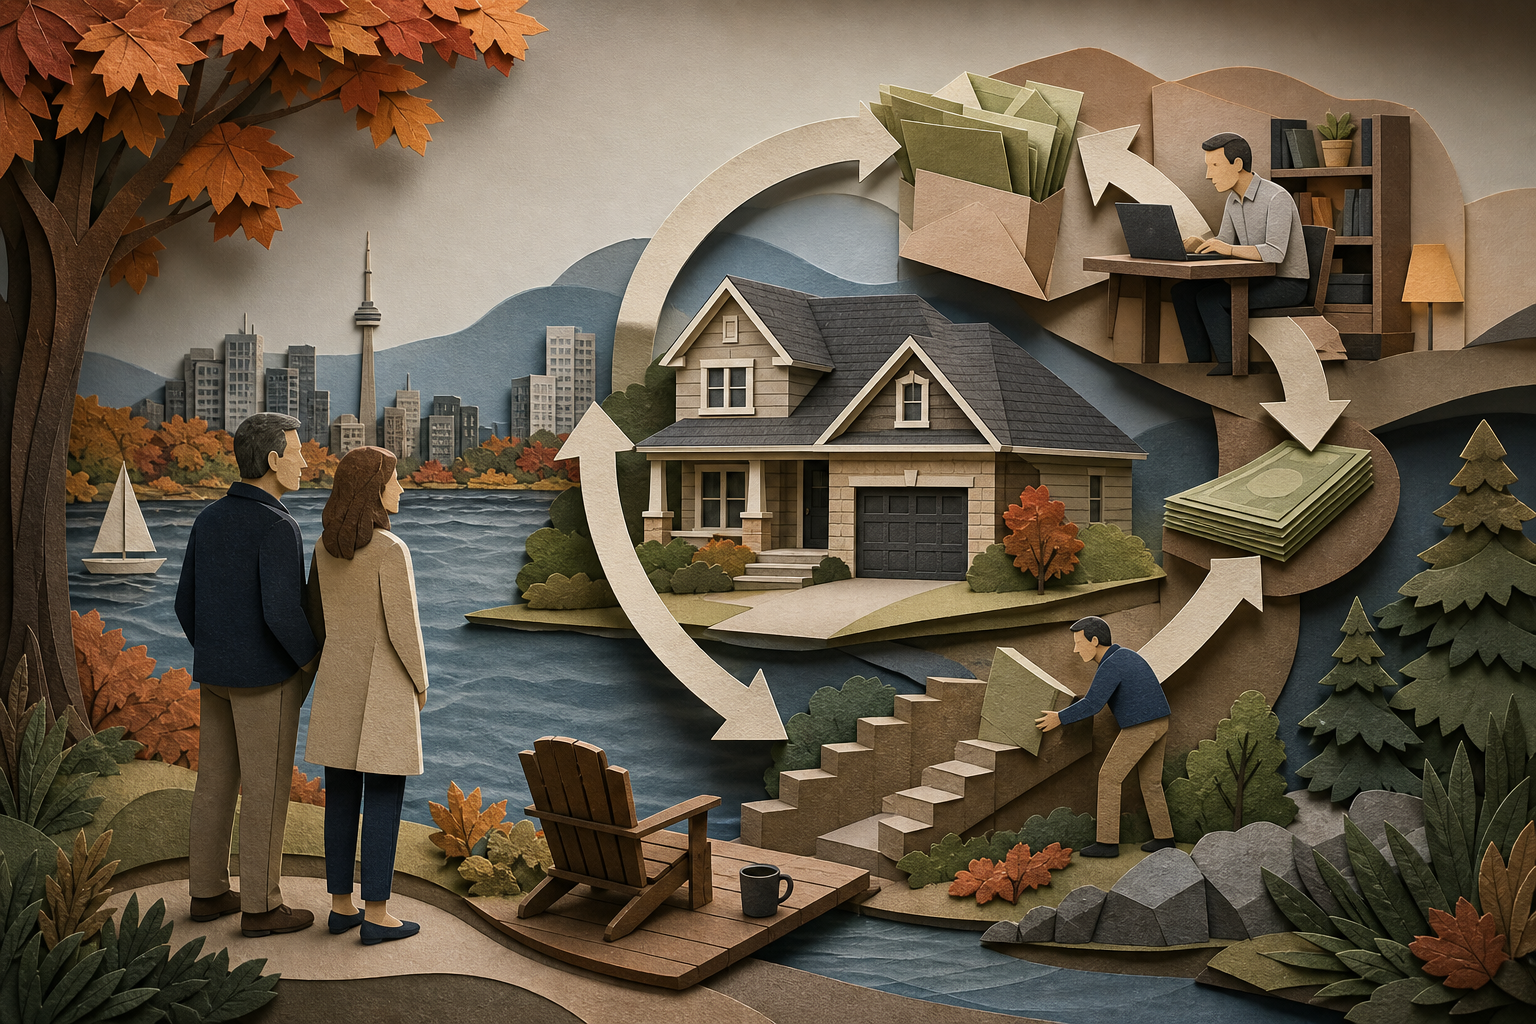
Most Canadian homeowners understand that paying down principal faster shortens amortization. What vanishes in the arithmetic is the difference between making one extra payment a year and making one extra payment that creates a new deductible loan, which generates a refund, which goes back onto the principal, which creates more deductible room. That loop is where the refund accelerates the payoff, typically shaving 3–8 years off a 25-year amortization.
Start with Mark. He's 48, lives in Burlington, carries a $420,000 mortgage at a mid-range fixed rate, 25 years remaining. Household income is $185,000. Marginal tax rate in Ontario: 43.41%. He has $80,000 in home equity and a readvanceable mortgage with a HELOC tied to it.
Path A: Extra Payments Without the Smith Manoeuvre™
Mark decides to put an extra $5,000 a year onto the mortgage. Over 25 years, those prepayments knock roughly 4 years off the amortization. He's mortgage-free at year 21 instead of year 25. The extra principal reduces interest costs by about $62,000 over the life of the loan. Solid.
Path B: The Smith Manoeuvre™ With Systematic Refund Deployment
Mark pays down $5,000 on the mortgage. The HELOC limit increases by $5,000. He borrows that $5,000 back and invests it in dividend-paying Canadian equities yielding 4.2%. The interest on the $5,000 HELOC advance is now tax-deductible because the borrowed money went into income-producing investments.
At a competitive HELOC rate near Prime, the $5,000 costs approximately $220-$230 in interest the first year. That interest is deductible. At his 43.41% marginal rate, the refund is $100. He takes that $100 and puts it back onto the mortgage principal. The HELOC limit goes up another $100. He borrows that $100, invests it, deducts the interest, gets another refund. And so on.
This is where the math diverges. The first-year refund is small. By year five, the cumulative deductible interest generates a refund of around $1,800. By year ten, the refund exceeds $4,000 annually. Each refund accelerates the mortgage payoff, which creates more HELOC room, which creates more deductible interest, which creates a larger refund. With systematic refund deployment, the mortgage payoff accelerates by 3–8 years, typically reaching zero between year 17 and year 22 of the original 25-year amortization. Typically reaching year 17–22 instead, depending on investment returns and market conditions.
Why Advisors Underestimate the Refund Velocity
Most financial planners model the Smith Manoeuvre™ as a debt-swap with a tax benefit. They calculate the annual deduction, apply the marginal rate, and show the client a static tax saving. What they miss is the feedback loop. The refund isn't income you spend. It's principal you redeploy, which accelerates the entire structure.
The difference isn't the size of the refund in year one. It's the compounding effect of redeploying that refund every single year for a decade. By year eight, the annual refund is covering more than half of Mark's original $5,000 prepayment. By year eleven, the refund alone is making the entire extra payment. The client is no longer funding the acceleration. The tax system is.
The Boundary Case
This works when three conditions hold. First, the client has sufficient equity to support a readvanceable mortgage structure, typically $40,000 minimum. Second, the marginal tax rate is high enough to make the deduction meaningful. Below 35%, the refund shrinks and the timeline stretches. Third, the HELOC rate and the investment return are close enough that the spread doesn't erode the benefit. If HELOC rates spike to 8% while dividends stay at 4%, the math breaks.
For Mark, those conditions hold. For a household earning $70,000 with a 20.5% marginal rate and $15,000 in equity, they don't. The strategy isn't universal. But when it fits, the timeline compression is real. Most advisors show the tax deduction. The refund velocity is what actually pays off the house.



Most Canadian homeowners understand that paying down principal faster shortens amortization. What vanishes in the arithmetic is the difference between making one extra payment a year and making one extra payment that creates a new deductible loan, which generates a refund, which goes back onto the principal, which creates more deductible room. That loop is where the refund accelerates the payoff, typically shaving 3–8 years off a 25-year amortization.
Start with Mark. He's 48, lives in Burlington, carries a $420,000 mortgage at a mid-range fixed rate, 25 years remaining. Household income is $185,000. Marginal tax rate in Ontario: 43.41%. He has $80,000 in home equity and a readvanceable mortgage with a HELOC tied to it.
Path A: Extra Payments Without the Smith Manoeuvre™
Mark decides to put an extra $5,000 a year onto the mortgage. Over 25 years, those prepayments knock roughly 4 years off the amortization. He's mortgage-free at year 21 instead of year 25. The extra principal reduces interest costs by about $62,000 over the life of the loan. Solid.
Path B: The Smith Manoeuvre™ With Systematic Refund Deployment
Mark pays down $5,000 on the mortgage. The HELOC limit increases by $5,000. He borrows that $5,000 back and invests it in dividend-paying Canadian equities yielding 4.2%. The interest on the $5,000 HELOC advance is now tax-deductible because the borrowed money went into income-producing investments.
At a competitive HELOC rate near Prime, the $5,000 costs approximately $220-$230 in interest the first year. That interest is deductible. At his 43.41% marginal rate, the refund is $100. He takes that $100 and puts it back onto the mortgage principal. The HELOC limit goes up another $100. He borrows that $100, invests it, deducts the interest, gets another refund. And so on.
This is where the math diverges. The first-year refund is small. By year five, the cumulative deductible interest generates a refund of around $1,800. By year ten, the refund exceeds $4,000 annually. Each refund accelerates the mortgage payoff, which creates more HELOC room, which creates more deductible interest, which creates a larger refund. With systematic refund deployment, the mortgage payoff accelerates by 3–8 years, typically reaching zero between year 17 and year 22 of the original 25-year amortization. Typically reaching year 17–22 instead, depending on investment returns and market conditions.
Why Advisors Underestimate the Refund Velocity
Most financial planners model the Smith Manoeuvre™ as a debt-swap with a tax benefit. They calculate the annual deduction, apply the marginal rate, and show the client a static tax saving. What they miss is the feedback loop. The refund isn't income you spend. It's principal you redeploy, which accelerates the entire structure.
The difference isn't the size of the refund in year one. It's the compounding effect of redeploying that refund every single year for a decade. By year eight, the annual refund is covering more than half of Mark's original $5,000 prepayment. By year eleven, the refund alone is making the entire extra payment. The client is no longer funding the acceleration. The tax system is.
The Boundary Case
This works when three conditions hold. First, the client has sufficient equity to support a readvanceable mortgage structure, typically $40,000 minimum. Second, the marginal tax rate is high enough to make the deduction meaningful. Below 35%, the refund shrinks and the timeline stretches. Third, the HELOC rate and the investment return are close enough that the spread doesn't erode the benefit. If HELOC rates spike to 8% while dividends stay at 4%, the math breaks.
For Mark, those conditions hold. For a household earning $70,000 with a 20.5% marginal rate and $15,000 in equity, they don't. The strategy isn't universal. But when it fits, the timeline compression is real. Most advisors show the tax deduction. The refund velocity is what actually pays off the house.
Sources
Read Next
Wells Fargo Says Rising Bond Yields Should Force You to Rethink Your Stock Portfolio
At the Top Tax Bracket, Every Dollar of Rental Interest Returns 53 Cents: Why the Smith Manoeuvre™ Is a High-Income Play
China's Treasury retreat to record lows rewrites the rules for bond investors
GIC Rates Below 4.2% Flip the Smith Manoeuvre™ Math From Marginal to Compelling