Turn your mortgage into a wealth-building tool. Smith Manoeuvre strategies, tax-smart planning, and honest math from two Canadian mortgage strategists.
Four Texas Gulf Coast Towns Where Flood Insurance Now Outweighs the Water View
A 1,200-square-foot beachfront condo in Galveston now carries an annual flood insurance premium of $12,000. That figure exceeds the monthly property tax and HOA fee combined. The premium didn't appear overnight. FEMA's Risk Rating 2.0 methodology, fully implemented by 2026, replaced subsidized legacy rates with actuarial pricing tied to individual property profiles. Coastal Texas, long pitched as the affordable alternative to Florida or California beachfront, is now experiencing a repricing that has collapsed the buyer pool in specific ZIP codes.
The shift isn't uniform. Inland properties twenty miles from the coast are largely unaffected. But in four towns ringing Galveston Bay and the open Gulf, insurance costs have become the primary constraint on who can afford to buy, hold, or finance a property. The towns share a pattern: high exposure to storm surge, limited private insurance availability, and a concentration of non-elevated older construction that the new rating system penalizes harshly.
Galveston: The Investor Exodus
Galveston has seen the steepest falloff in sight-unseen investor activity. Properties that previously attracted out-of-state buyers for rental income now require $8,000 to $15,000 in annual flood premiums for structures built before modern elevation standards. Texas Property Code § 5.020 mandates disclosure if a property sits in a 100-year floodplain. That disclosure, combined with the premium quote delivered at closing, is killing deals.
Lenders require flood coverage for any federally backed mortgage in high-risk zones. If a buyer cannot afford the insurance, they cannot close the loan. The result is a de facto shift to cash-only transactions, which limits the market to wealthy buyers who can either self-insure or absorb the premium as a cost of ownership rather than a financing hurdle. Middle-income families, who once made up the bulk of Galveston's residential market, are being priced out not by the purchase price but by the annual carrying cost.
Surfside Beach: The Retrofit Trap
Surfside Beach is experiencing a version of the same problem with a structural twist. Elevation retrofits, which involve lifting an existing home onto piers or pilings, can reduce premiums by 40% to 60%. The work costs $50,000 to $100,000 depending on square footage and soil conditions. For a buyer purchasing a $300,000 property, that retrofit expense functionally raises the entry price to $400,000, assuming they can finance the work at all. Most lenders will not roll mitigation costs into the mortgage.
The town is caught between two incompatible financial realities: properties priced for their current condition, and insurance rates priced for their flood exposure. Sellers who refuse to drop asking prices to account for the retrofit burden are watching listings sit for six months or longer.
Port Aransas and Rockport: The TWIA Surcharge Layer
Port Aransas and Rockport face the added burden of the Texas Windstorm Insurance Association (TWIA), the state's insurer of last resort for wind and hail in 14 coastal counties. TWIA premiums are climbing alongside federal flood rates. A buyer in Port Aransas now budgets for two separate catastrophic insurance policies before factoring in standard homeowner's coverage. Combined annual premiums in the $18,000 to $25,000 range are common for waterfront properties.
That expense changes the investment math entirely. For short-term rental operators, insurance is now the largest single operating cost, outpacing mortgage interest, property management, and maintenance. Cap rates that looked viable in 2023 no longer pencil at 2026 premium levels. Owners are either exiting or shifting properties to long-term rentals where the insurance burden can be partially offset by stable occupancy.
The Market Response
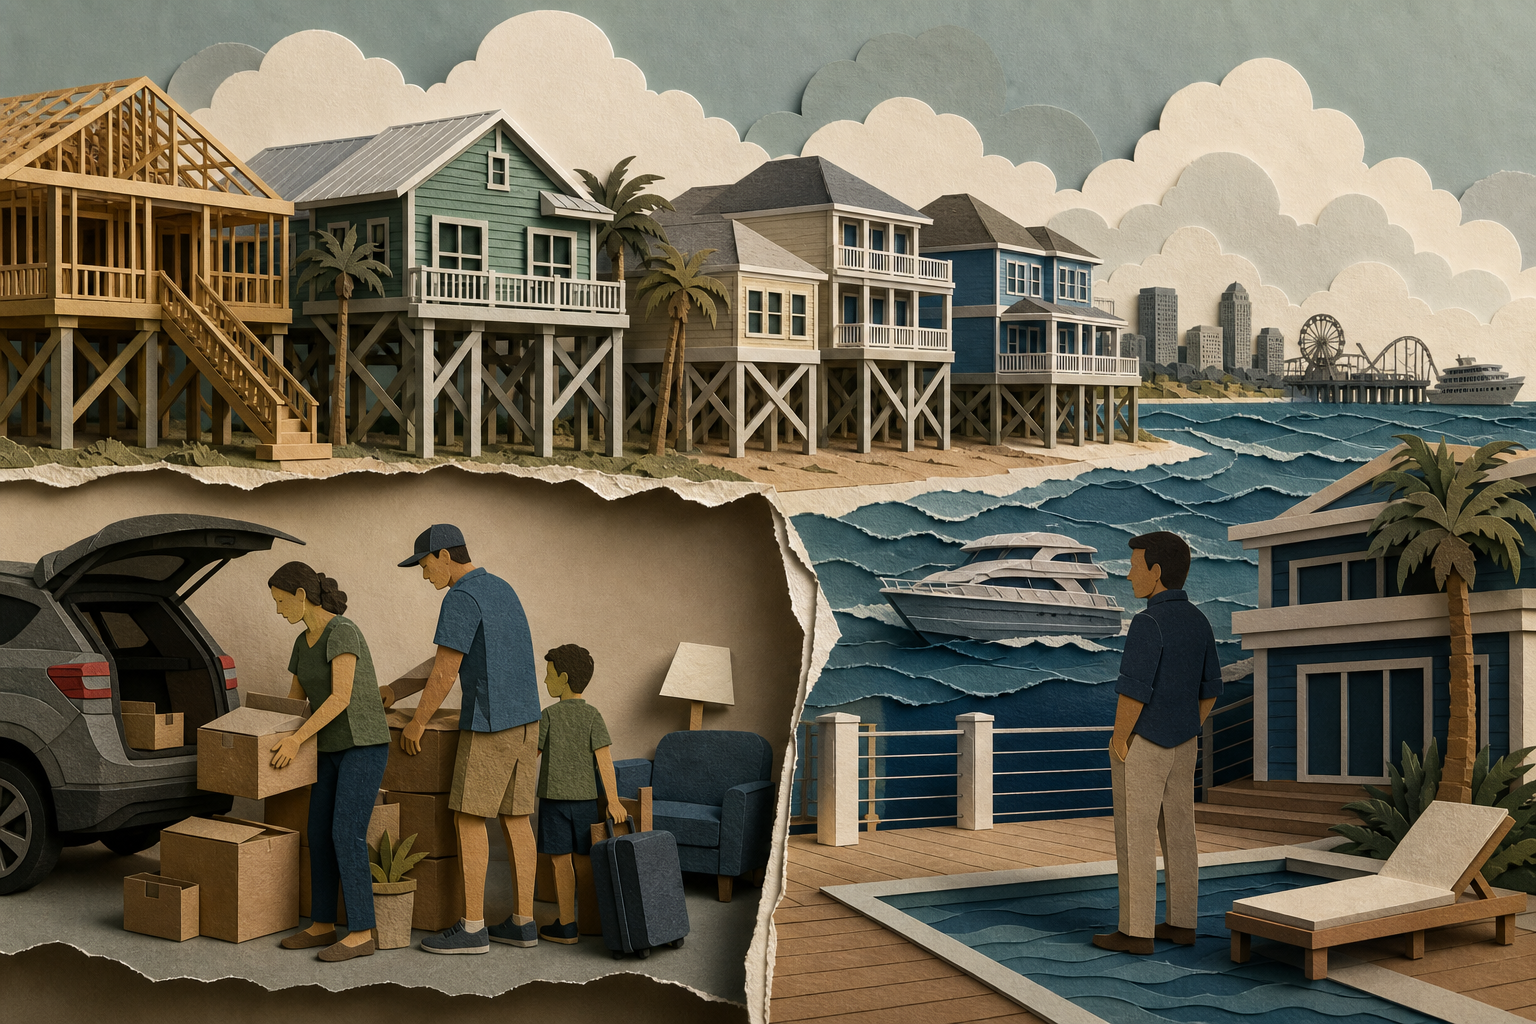
Architecture is adapting. New construction in all four towns is now almost exclusively elevated on piers, not because buyers prefer the aesthetic but because unfinanced, non-elevated homes are becoming unsellable. The "stilt house" has shifted from design choice to financial necessity.
Buyer migration is also underway, but it is measured in miles rather than states. Families are choosing towns 20 to 30 miles inland where flood zones and TWIA surcharges do not apply. The Texas Gulf Coast remains attractive. The specific ZIP codes where FEMA and TWIA premiums converge are becoming the domain of cash buyers wealthy enough to treat insurance as overhead rather than obstacle.



A 1,200-square-foot beachfront condo in Galveston now carries an annual flood insurance premium of $12,000. That figure exceeds the monthly property tax and HOA fee combined. The premium didn't appear overnight. FEMA's Risk Rating 2.0 methodology, fully implemented by 2026, replaced subsidized legacy rates with actuarial pricing tied to individual property profiles. Coastal Texas, long pitched as the affordable alternative to Florida or California beachfront, is now experiencing a repricing that has collapsed the buyer pool in specific ZIP codes.
The shift isn't uniform. Inland properties twenty miles from the coast are largely unaffected. But in four towns ringing Galveston Bay and the open Gulf, insurance costs have become the primary constraint on who can afford to buy, hold, or finance a property. The towns share a pattern: high exposure to storm surge, limited private insurance availability, and a concentration of non-elevated older construction that the new rating system penalizes harshly.
Galveston: The Investor Exodus
Galveston has seen the steepest falloff in sight-unseen investor activity. Properties that previously attracted out-of-state buyers for rental income now require $8,000 to $15,000 in annual flood premiums for structures built before modern elevation standards. Texas Property Code § 5.020 mandates disclosure if a property sits in a 100-year floodplain. That disclosure, combined with the premium quote delivered at closing, is killing deals.
Lenders require flood coverage for any federally backed mortgage in high-risk zones. If a buyer cannot afford the insurance, they cannot close the loan. The result is a de facto shift to cash-only transactions, which limits the market to wealthy buyers who can either self-insure or absorb the premium as a cost of ownership rather than a financing hurdle. Middle-income families, who once made up the bulk of Galveston's residential market, are being priced out not by the purchase price but by the annual carrying cost.
Surfside Beach: The Retrofit Trap
Surfside Beach is experiencing a version of the same problem with a structural twist. Elevation retrofits, which involve lifting an existing home onto piers or pilings, can reduce premiums by 40% to 60%. The work costs $50,000 to $100,000 depending on square footage and soil conditions. For a buyer purchasing a $300,000 property, that retrofit expense functionally raises the entry price to $400,000, assuming they can finance the work at all. Most lenders will not roll mitigation costs into the mortgage.
The town is caught between two incompatible financial realities: properties priced for their current condition, and insurance rates priced for their flood exposure. Sellers who refuse to drop asking prices to account for the retrofit burden are watching listings sit for six months or longer.
Port Aransas and Rockport: The TWIA Surcharge Layer
Port Aransas and Rockport face the added burden of the Texas Windstorm Insurance Association (TWIA), the state's insurer of last resort for wind and hail in 14 coastal counties. TWIA premiums are climbing alongside federal flood rates. A buyer in Port Aransas now budgets for two separate catastrophic insurance policies before factoring in standard homeowner's coverage. Combined annual premiums in the $18,000 to $25,000 range are common for waterfront properties.
That expense changes the investment math entirely. For short-term rental operators, insurance is now the largest single operating cost, outpacing mortgage interest, property management, and maintenance. Cap rates that looked viable in 2023 no longer pencil at 2026 premium levels. Owners are either exiting or shifting properties to long-term rentals where the insurance burden can be partially offset by stable occupancy.
The Market Response
Architecture is adapting. New construction in all four towns is now almost exclusively elevated on piers, not because buyers prefer the aesthetic but because unfinanced, non-elevated homes are becoming unsellable. The "stilt house" has shifted from design choice to financial necessity.
Buyer migration is also underway, but it is measured in miles rather than states. Families are choosing towns 20 to 30 miles inland where flood zones and TWIA surcharges do not apply. The Texas Gulf Coast remains attractive. The specific ZIP codes where FEMA and TWIA premiums converge are becoming the domain of cash buyers wealthy enough to treat insurance as overhead rather than obstacle.
Read Next
Wells Fargo Says Rising Bond Yields Should Force You to Rethink Your Stock Portfolio
At the Top Tax Bracket, Every Dollar of Rental Interest Returns 53 Cents: Why the Smith Manoeuvre™ Is a High-Income Play
China's Treasury retreat to record lows rewrites the rules for bond investors
GIC Rates Below 4.2% Flip the Smith Manoeuvre™ Math From Marginal to Compelling