Turn your mortgage into a wealth-building tool. Smith Manoeuvre strategies, tax-smart planning, and honest math from two Canadian mortgage strategists.
Canada's Rental Incentives Are Solving One Crisis by Creating Another
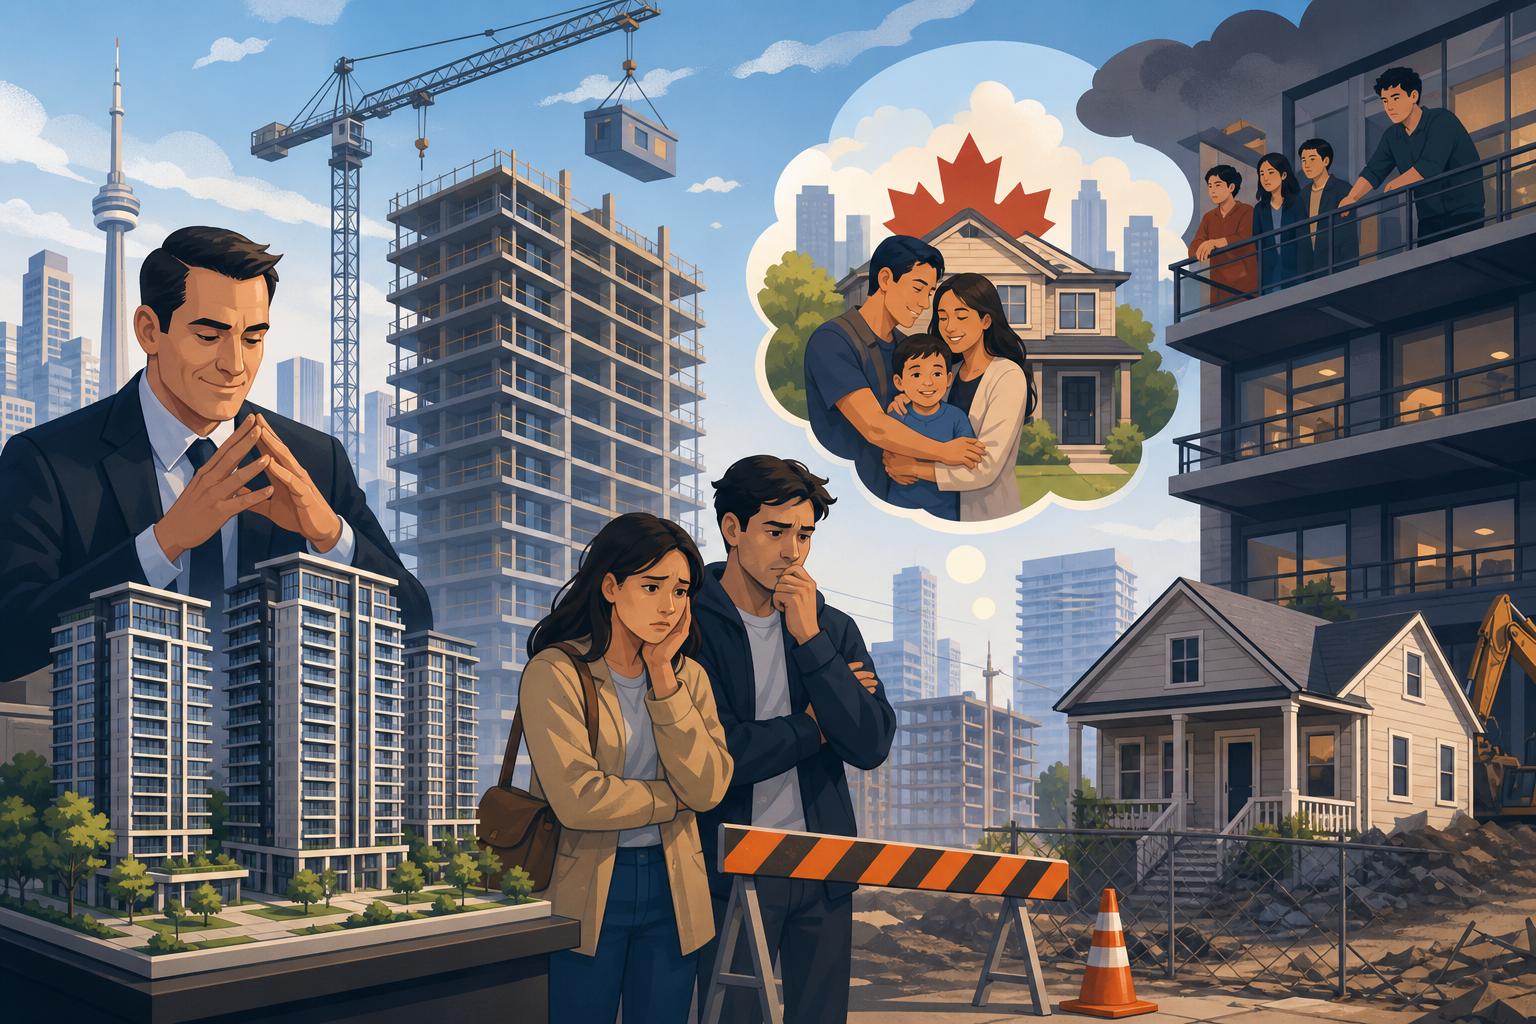
A Toronto developer stood in front of 400 unsold condo units last fall and made a choice: convert the entire tower to rental or walk away from the project entirely. He picked rentals. So did 47 other developers across Ontario in 2024, according to Urbanation's year-end tally. The federal GST rebate made the math work. High interest rates made everything else impossible.
Canada is now building rental housing at a pace not seen since the 1970s. Roughly 130,000 purpose-built rental units were under construction nationwide as of late 2024, per Desjardins. That's the headline. The footnote is that we're building far fewer ownership units than we did three years ago, and the gap is widening. Pre-construction condo sales in the Greater Toronto Area hit a 10-year low in 2024. Vancouver's numbers look worse. The projects that would have been condos are now rentals, or they're stalled, or they're dead.
Why the Pivot Happened
For years, the Canadian housing model ran on a specific fuel: individual investors buying pre-construction condos. They put down 15-20% deposits, developers used that cash to secure construction financing, and the building went up. When rates were low and appreciation was reliable, it worked. When the Bank of Canada pushed its policy rate above 5%, the carrying costs on a $650,000 one-bedroom condo in Toronto went from break-even to a $400-per-month bleed. Investors stopped buying. Developers couldn't get the deposits. The financing didn't close.
The federal response was the GST rebate on new rental construction, introduced in late 2023. Remove 5% from the cost structure and suddenly a stalled condo project pencils as a rental tower. Add in low-cost CMHC financing for purpose-built rentals and you've created a viable alternative channel. Developers took it. They had no choice.
The Wealth Transfer Nobody's Naming
Home equity has been the primary wealth-building vehicle for the Canadian middle class since the 1980s. A household that bought in 2010 and held through 2021 saw their net worth double, not from income but from the asset under their name. A household that rents, even in a stable tenancy, builds nothing. The gap compounds.
The shift to rental-dominant construction doesn't just change the tenure mix. It changes who accumulates wealth in this country. A 28-year-old looking to buy in 2026 faces a market where new supply is overwhelmingly rental and resale inventory is thin. Prices on the ownership stock that does exist stay elevated because there's no pipeline of new condos coming to market. The rental stock grows, which helps with immediate vacancy pressure, but it also locks more households into a position where they're paying someone else's mortgage instead of their own.
Germany and Switzerland run on rental models and they work, but those systems were built over generations with strong tenant protections and below-market social housing. Canada is landing in a rentership society by accident, through a policy designed to prevent a construction freeze, and we're doing it without the regulatory infrastructure that makes long-term renting viable for wealth building.
The Institutional Consolidation
The other shift is who owns the new rental stock. The condo era was retail investors, nurses, electricians, accountants buying one unit as a retirement hedge. The purpose-built rental era is REITs and pension funds buying entire buildings. The economics are different. An individual landlord might sell when they need liquidity or when the tenant turns difficult. An institutional landlord holds the asset for 30 years as part of a diversified portfolio. That creates stability of tenancy, which is real, but it also means the rental stock is permanently rental. There's no chance that unit converts to ownership down the road.
Before 2008, roughly 68% of Canadian households owned their home. We're now tracking toward 62%, and the pipeline suggests that's the floor, not a blip. The rental incentives solved the immediate crisis, which was a total freeze in construction starts. What they didn't solve, and what they may have worsened, is the longer crisis of who gets to build equity in this country and who doesn't.



A Toronto developer stood in front of 400 unsold condo units last fall and made a choice: convert the entire tower to rental or walk away from the project entirely. He picked rentals. So did 47 other developers across Ontario in 2024, according to Urbanation's year-end tally. The federal GST rebate made the math work. High interest rates made everything else impossible.
Canada is now building rental housing at a pace not seen since the 1970s. Roughly 130,000 purpose-built rental units were under construction nationwide as of late 2024, per Desjardins. That's the headline. The footnote is that we're building far fewer ownership units than we did three years ago, and the gap is widening. Pre-construction condo sales in the Greater Toronto Area hit a 10-year low in 2024. Vancouver's numbers look worse. The projects that would have been condos are now rentals, or they're stalled, or they're dead.
Why the Pivot Happened
For years, the Canadian housing model ran on a specific fuel: individual investors buying pre-construction condos. They put down 15-20% deposits, developers used that cash to secure construction financing, and the building went up. When rates were low and appreciation was reliable, it worked. When the Bank of Canada pushed its policy rate above 5%, the carrying costs on a $650,000 one-bedroom condo in Toronto went from break-even to a $400-per-month bleed. Investors stopped buying. Developers couldn't get the deposits. The financing didn't close.
The federal response was the GST rebate on new rental construction, introduced in late 2023. Remove 5% from the cost structure and suddenly a stalled condo project pencils as a rental tower. Add in low-cost CMHC financing for purpose-built rentals and you've created a viable alternative channel. Developers took it. They had no choice.
The Wealth Transfer Nobody's Naming
Home equity has been the primary wealth-building vehicle for the Canadian middle class since the 1980s. A household that bought in 2010 and held through 2021 saw their net worth double, not from income but from the asset under their name. A household that rents, even in a stable tenancy, builds nothing. The gap compounds.
The shift to rental-dominant construction doesn't just change the tenure mix. It changes who accumulates wealth in this country. A 28-year-old looking to buy in 2026 faces a market where new supply is overwhelmingly rental and resale inventory is thin. Prices on the ownership stock that does exist stay elevated because there's no pipeline of new condos coming to market. The rental stock grows, which helps with immediate vacancy pressure, but it also locks more households into a position where they're paying someone else's mortgage instead of their own.
Germany and Switzerland run on rental models and they work, but those systems were built over generations with strong tenant protections and below-market social housing. Canada is landing in a rentership society by accident, through a policy designed to prevent a construction freeze, and we're doing it without the regulatory infrastructure that makes long-term renting viable for wealth building.
The Institutional Consolidation
The other shift is who owns the new rental stock. The condo era was retail investors, nurses, electricians, accountants buying one unit as a retirement hedge. The purpose-built rental era is REITs and pension funds buying entire buildings. The economics are different. An individual landlord might sell when they need liquidity or when the tenant turns difficult. An institutional landlord holds the asset for 30 years as part of a diversified portfolio. That creates stability of tenancy, which is real, but it also means the rental stock is permanently rental. There's no chance that unit converts to ownership down the road.
Before 2008, roughly 68% of Canadian households owned their home. We're now tracking toward 62%, and the pipeline suggests that's the floor, not a blip. The rental incentives solved the immediate crisis, which was a total freeze in construction starts. What they didn't solve, and what they may have worsened, is the longer crisis of who gets to build equity in this country and who doesn't.
Read Next
Wells Fargo Says Rising Bond Yields Should Force You to Rethink Your Stock Portfolio
At the Top Tax Bracket, Every Dollar of Rental Interest Returns 53 Cents: Why the Smith Manoeuvre™ Is a High-Income Play
China's Treasury retreat to record lows rewrites the rules for bond investors
GIC Rates Below 4.2% Flip the Smith Manoeuvre™ Math From Marginal to Compelling